<div class="bd">
<div class="content" style="height:auto;">
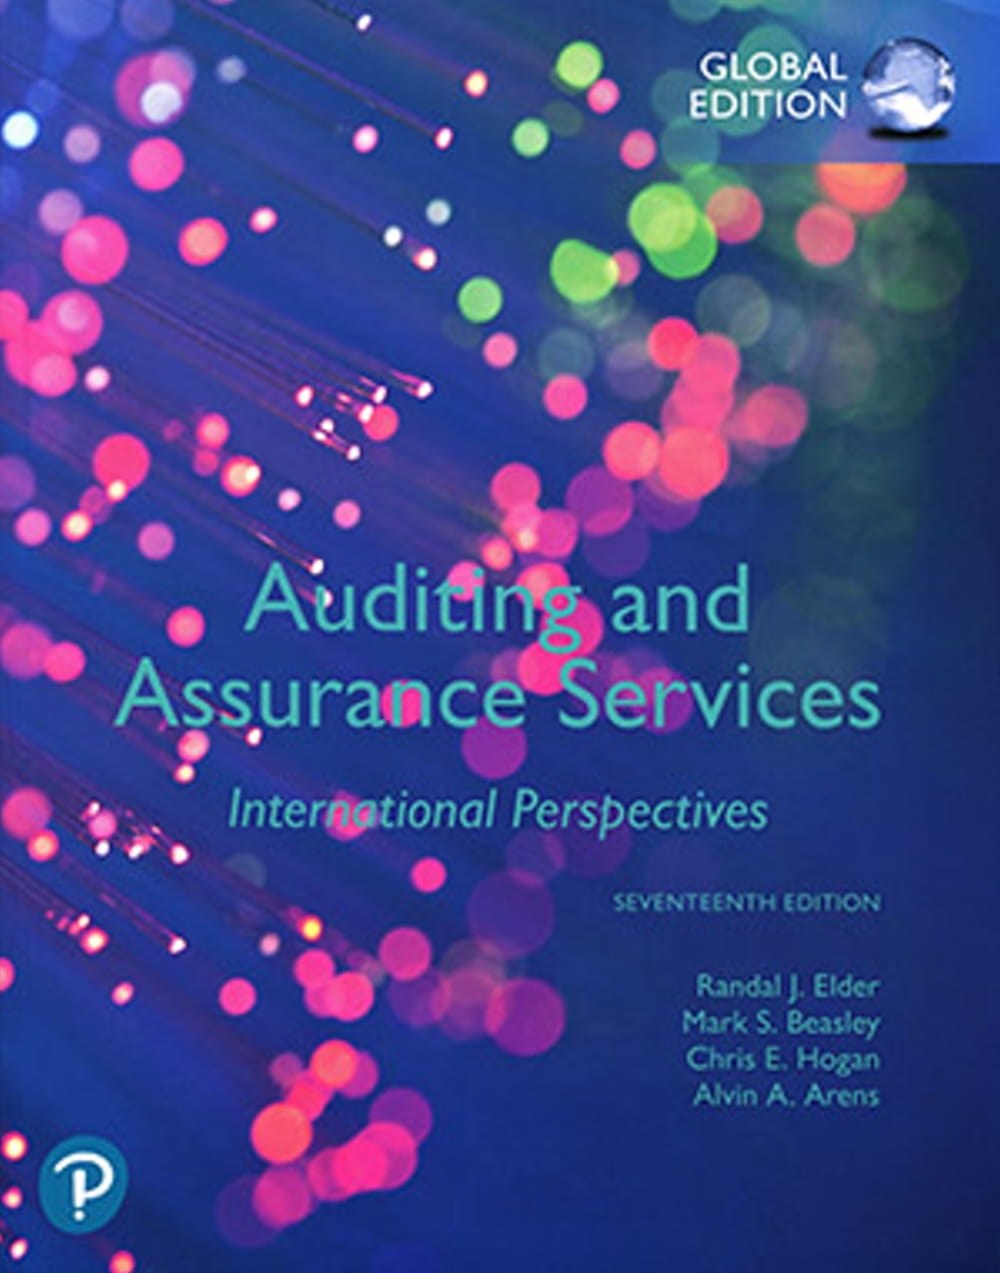
Comprehensive and up-to-date, including discussion of new standards, codes, and concepts, Auditing and Assurance Services: An Integrated Approach presents an integrated approach to auditing that details the process from start to finish. Based on the authors’ belief that the fundamental concepts of auditing centre on the nature and amount of evidence that auditors should gather in specific engagements, the text’s primary objective is to illustrate auditing concepts using practical examples and real-world settings. Using key real audit decisions as their foundation, students can successfully conduct an audit according to a financial reporting framework.
</div><div class="type02_gradient" style="display:none;"></div>
</div></div><div class="mod_b type02_m057 clearfix">
<a name="AuthorP00a400020009"> </a>
目 錄
<div class="bd">
<div class="content more_off" id="M201105_0_getProdTextInfo_P00a400020009_h2">
<strong>PART I: THE AUDITING PROFESSION</strong><br>
Ch 1 The Demand for Audit and Other Assurance Services<br>
Ch 2 The CPA Profession<br>
Ch 3 Other Assurance Services<br>
Ch 4 Internal and Governmental Financial Auditing and Operational Auditing<br>
<br>
<strong>PART II: THE AUDIT PROCESS</strong><br>
Ch 5 Audit Responsibilities and Objectives<br>
Ch 6 Audit Evidence<br>
Ch 7 Audit Planning and Materiality<br>
Ch 8 Assessing the Risk of Material Misstatement<br>
Ch 9 Assessing and Responding to Fraud Risks<br>
Ch10 Internal Control and COSO Framework<br>
Ch11 Assessing Control Risk and Reporting on Internal Controls<br>
Ch12 Overall Audit Strategy and Audit Program<br>
<br>
<strong>PART III: APPLICATION OF THE AUDIT PROCESS TO THE SALES AND COLLECTION CYCLE</strong><br>
Ch13 Audit of the Sales and Collection Cycle: Tests of Controls and Substantive Tests of Transactions<br>
Ch14 Audit Sampling for Tests of Controls and Substantive Tests of Transactions<br>
Ch15 Completing the Tests in the Sales and Collection Cycle: Accounts Receivable<br>
Ch16 Audit Sampling for Tests of details of Balances<br>
<br>
<strong>PART IV: APPLICATION OF THE AUDIT PROCESS TO OTHER CYCLES</strong><br>
Ch17 Audit of the Acquisition and Payment Cycle: Tests of Controls, Substantive Tests of Transactions, and Accounts Payable<br>
Ch18 Completing the Tests in the Acquisition and Payment Cycle: Verification of Selected Accounts<br>
Ch19 Audit of the Payroll and Personnel Cycle<br>
Ch20 Audit of the Inventory and Warehousing Cycle<br>
Ch21 Audit of the Capital Acquisition and Repayment Cycle<br>
Ch22 Audit of Cash and Financial Instruments<br>
<br>
<strong>PART V: COMPLETING THE AUDIT</strong><br>
Ch23 Completing the Audit<br>
Ch24 Audit Reports<br>
Ch25 Professional Ethics
</div>